Mortgage and protection in Dorset
Mortgage & Protection Advice Across Dorset
From your first purchase to a change of home or a mortgage review, Conrad Financial Services helps you understand your options across Dorset. We bring mortgage and protection advice together, so your property plans and the people who depend on you are considered in the same conversation.
Find advice for your area
Local Mortgage And Protection Advice Across Dorset
Explore detailed local guidance for Poole and Parkstone, Bournemouth, Wareham, Christchurch, Wimborne, Ferndown, Dorchester, Weymouth, Blandford Forum, Swanage, Shaftesbury and Gillingham. Conrad Financial Services also supports clients across wider Dorset, with mortgage and protection advice shaped around your circumstances, the property and your plans.


Our local base
Poole And Parkstone
Mortgage and protection guidance for Poole, Parkstone and nearby communities, including useful questions about leasehold flats, waterfront homes and local property searches.
Nearby area: Broadstone mortgage and protection guidance
Explore Poole and Parkstone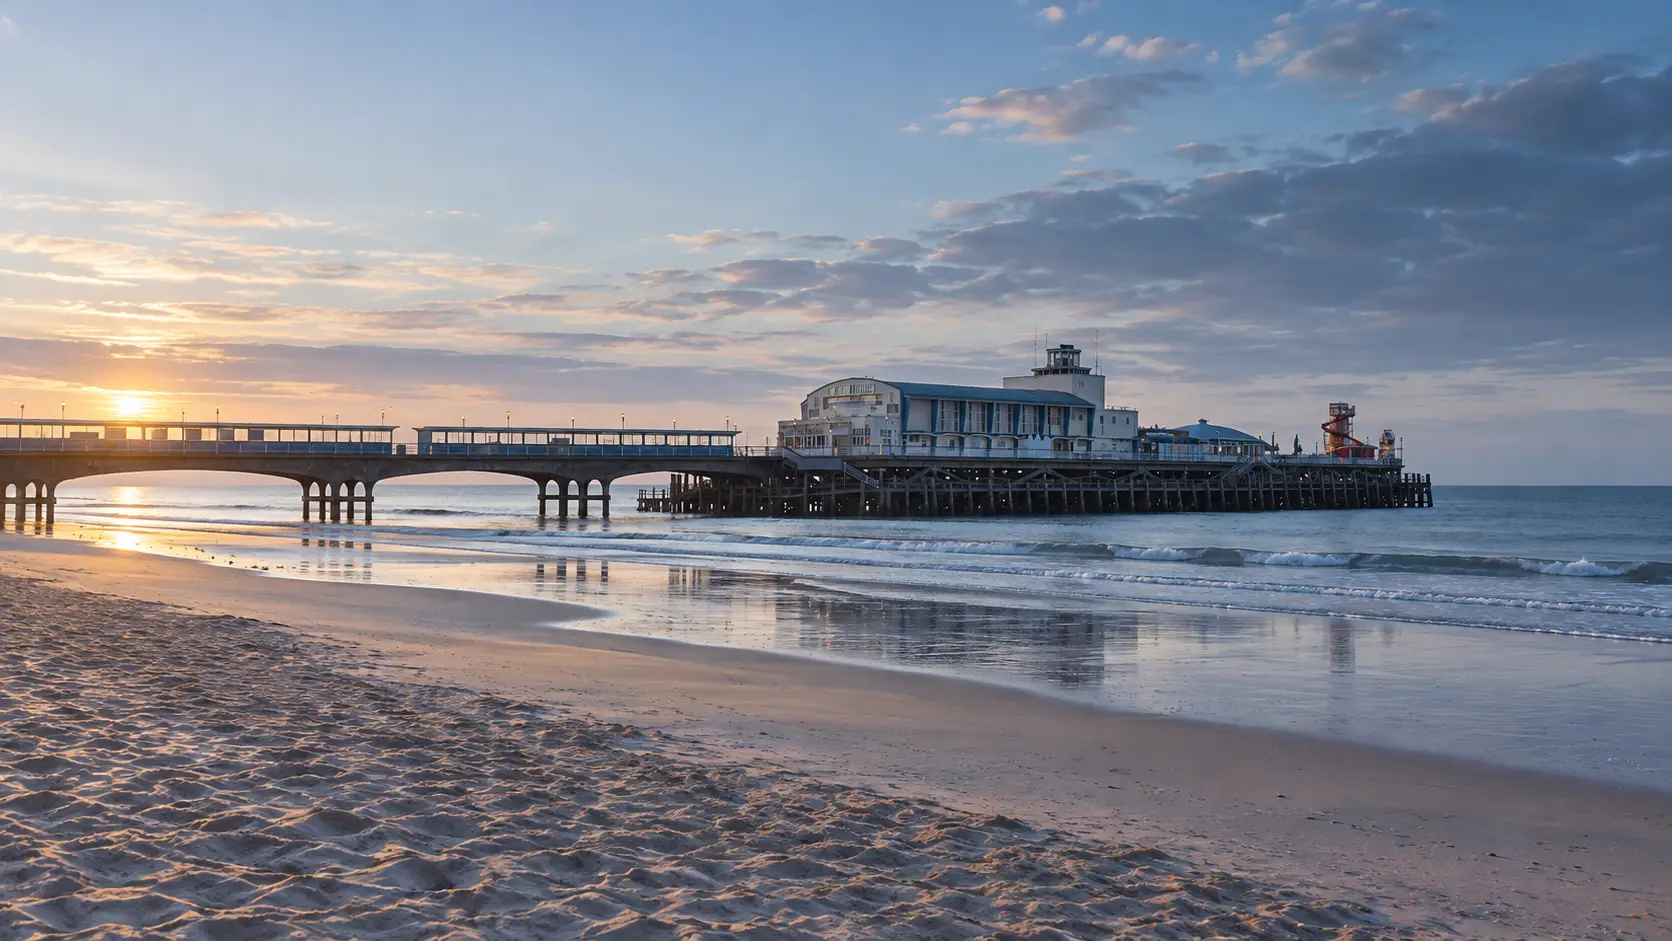
Coastal Dorset
Bournemouth
Mortgage and protection guidance for Bournemouth buyers, home movers and homeowners, including useful questions about flats, leasehold terms and the costs of buying near the coast.
Explore Bournemouth mortgage advice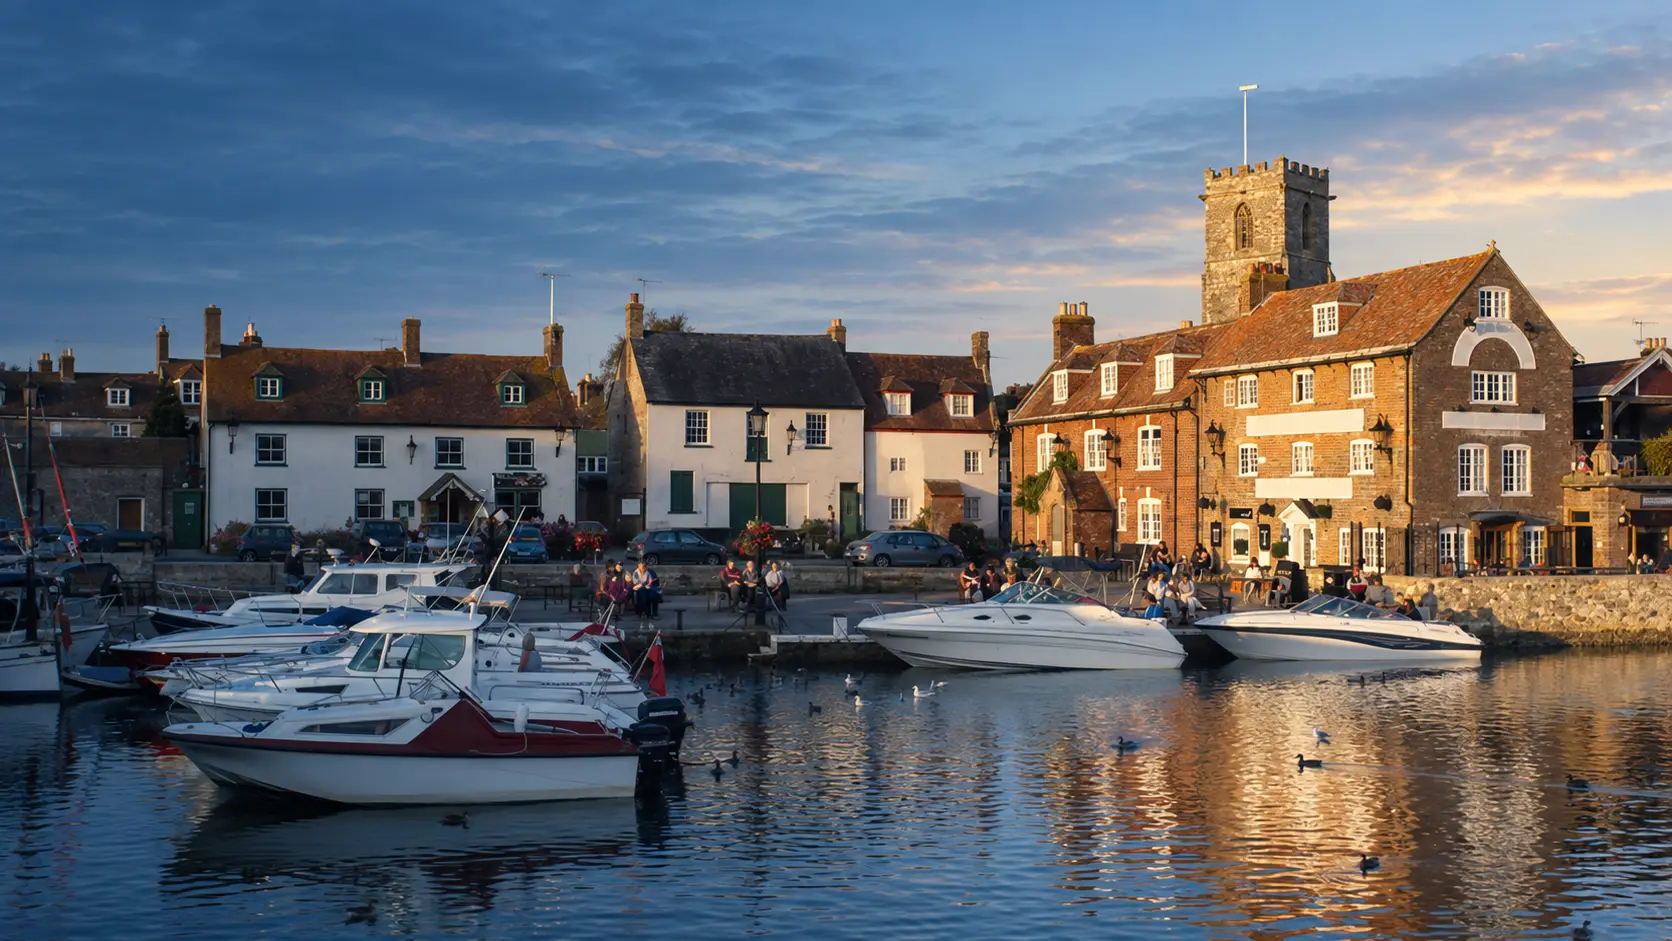
Purbeck and the Frome
Wareham
Mortgage and protection guidance for Wareham and nearby Purbeck communities, including questions about moving home, conservation areas, flood information and property-specific lender checks.
Nearby area: Wool mortgage and protection guidance
Explore Wareham mortgage advice
Christchurch and the Stour
Christchurch
Mortgage and protection guidance for Christchurch buyers and homeowners, including local questions about harbour and river locations, conservation areas, leasehold flats and property-specific lender checks.
Explore Christchurch mortgage advice
Historic East Dorset
Wimborne
Mortgage and protection advice for Wimborne, Colehill and Corfe Mullen, with property-specific guidance for older homes, alterations, environmental searches and different income structures.
Nearby areas: Colehill and Corfe Mullen guidance
Explore Wimborne mortgage advice
East Dorset communities
Ferndown
Mortgage and protection advice for Ferndown, West Parley, Longham and West Moors, including established homes, newer developments and address-specific property checks.
Nearby areas: West Parley, Longham and West Moors guidance
Explore Ferndown mortgage advice
County town and Poundbury
Dorchester
Mortgage and protection advice for Dorchester and Poundbury, with practical guidance on older or altered homes, newer purchases, estate arrangements and recurring property charges.
Nearby area: Poundbury mortgage and protection guidance
Explore Dorchester mortgage advice
Town, coast and nearby communities
Weymouth
Mortgage and protection advice for Weymouth, Chickerell and Portland, including leasehold, intended-use, construction and address-specific property questions.
Nearby areas: Chickerell and Portland mortgage guidance
Explore Weymouth mortgage advice
Your home and the wider budget
Blandford Forum
Mortgage and protection advice for Blandford Forum and Blandford St Mary, with practical preparation for buying, remortgaging and planned work.
Nearby area: Blandford St Mary mortgage and protection guidance
Explore Blandford Forum mortgage advice
Planning for life by the coast
Swanage
Mortgage and protection advice for Swanage and Herston, bringing your income, moving plans and property questions into one conversation.
Nearby area: Herston mortgage and protection guidance
Explore Swanage mortgage advice
Keep the mortgage and move aligned
Shaftesbury
Mortgage and protection advice for Shaftesbury and Cann, with a clear plan for the deposit, application, mortgage offer and completion timetable.
Nearby area: Cann mortgage and protection guidance
Explore Shaftesbury mortgage advice
Compare the mortgage with the monthly budget
Gillingham
Mortgage and protection advice for Gillingham and Milton-on-Stour, bringing the proposed mortgage, property costs and household commitments into one plan.
Nearby area: Milton-on-Stour mortgage and protection guidance
Explore Gillingham mortgage advice
Across the county
Wider Dorset
Mortgage and protection advice for clients across Dorset, including Bridport, Sherborne and other surrounding communities.
Ask about mortgage and protection advice in your areaBefore you choose a property
Look Beyond The Asking Price
The right questions depend on the home and how you intend to use it. These county-wide starting points complement, rather than replace, property-specific legal advice and mortgage assessment.
Use The Right Local Authority
Dorset Council and Bournemouth, Christchurch and Poole Council cover different areas. Check which council serves the property before looking for planning information or housing schemes. Do not assume statistics labelled “Dorset” include Poole and Bournemouth.
Find the property’s councilCheck The Full Cost Of Shared Ownership
Dorset Council provides information about shared ownership and organisations offering these homes. If you are considering this route, ask about the mortgage, rent on the remaining share, service charges and future costs. Available homes, eligibility and lender acceptance must be checked separately.
Explain Your Plans For The Home
Tell your adviser whether you will live in the property or let it, and about any intended changes. Ask your conveyancer to explain relevant planning conditions and other restrictions revealed by searches. A suitable mortgage cannot be assumed from the listing or postcode alone.
What local land searches can showUnderstand the geography
Two Local Areas, Not One County Average
Select Dorset for the Dorset Council area, or BCP for Bournemouth, Christchurch and Poole. These are separate official data areas; neither figure is an average for every home across the wider county.
The figures provide historical context, not a valuation or a borrowing limit. The first-time-buyer figure is an average purchase price, not the deposit or mortgage needed. Source, data period and last data check are shown alongside the figures.
Mortgage advice across Dorset
Mortgage Advice Matched To Your Plans
Whether you are buying your first home in Dorset, moving, remortgaging or earning through a business or contract, the right route depends on your circumstances as well as the property.
Conrad Financial Services considers your income, commitments, deposit or equity and future plans before making a recommendation. Any mortgage remains subject to the lender’s criteria, assessment and approval.
First-Time Buyers
Understand the deposit, wider buying costs and information a lender may need before you make an offer.
First-time buyer mortgages
Moving Home
Consider your current mortgage, onward purchase, moving costs and the timing of your plans together.
Home mover mortgages
Remortgaging
Review your current deal, early repayment charges, fees and future plans before deciding whether to switch.
Remortgage advice
Company, Self-Employed Or Contract Income
Lenders assess salary, dividends, accounts, retained profit and professional contract income differently. We review how you earn and the evidence available.
More than the mortgage
Protection Planning For Dorset Households
Dorset households can have very different property, income and family commitments. Conrad Financial Services can discuss the financial effect of illness, time away from work or death, whether or not we are arranging your mortgage.
Explore protection advice
Life insurance, critical illness cover and income protection serve different purposes. A review considers who depends on you, household commitments, earnings, savings, employer benefits and any existing policies.
The appropriate conversation depends on your needs rather than your Dorset postcode, and protection advice can be provided separately from mortgage advice.
Cover is subject to insurer terms, exclusions, underwriting and acceptance. Benefits and waiting periods vary, and not every event is covered. Keep existing protection in place until you understand the implications of any change and replacement cover has started.
What happens next
How Mortgage And Protection Advice Works
Begin with the outcome you want to achieve and the way you prefer to meet. We then establish the financial and property information needed, research relevant options and explain any recommendation and fees before you decide how to proceed.
Set Out Your Objective
Explain whether your priority is buying, moving, remortgaging or reviewing protection.
Confirm The Relevant Details
We establish the income, commitments, deposit or equity and property information needed.
Research The Available Routes
Relevant lender or insurer criteria are considered against your circumstances and objectives.
Explain Costs And Conditions
We talk through the proposed arrangement, fees, exclusions and important conditions.
Decide Whether To Apply
You decide whether to proceed after the recommendation and next steps have been explained.
Support The Application
When instructed, we prepare the application and remain involved during assessment.
Mortgage & protection questions
Your Dorset Mortgage And Protection Questions
The questions below cover county-wide mortgage and protection themes. For place-specific property matters, follow the Poole, Bournemouth or Wareham guides. Any recommendation requires an individual assessment.
Do I Need A Mortgage Broker Based In Dorset?
No. A mortgage adviser does not need to be in the same town as you or the property. The important point is that any recommendation is based on your circumstances, the proposed property and the lender’s criteria.
Conrad Financial Services is based in Parkstone, Poole and provides mortgage and protection advice by telephone and video across England and Wales. Adviser visits can be discussed by arrangement.
How Much Deposit Do I Need To Buy A Home In Dorset?
The deposit required depends on the property, the lender’s criteria and your circumstances. Your income, regular commitments, credit history and whether you are buying a house, flat or another property type may affect the mortgages available.
A larger deposit can sometimes provide access to a wider range of products, but this is not guaranteed. Area-average house prices do not determine the deposit you personally need.
How Much Could I Borrow For A Mortgage In Dorset?
Lenders normally consider income, expenditure, existing credit commitments, deposit, credit history and the proposed property. Each lender applies its own affordability assessment and criteria.
The Dorset and BCP figures on this page are market context only. They are not a borrowing limit, valuation or indication that a mortgage will be available.
Can Conrad Financial Services Help First-Time Buyers In Dorset?
Yes. We can help first-time buyers understand their potential budget, deposit, wider buying costs, application process and the information a lender may require.
If appropriate, we can also help arrange an agreement in principle. This is not a mortgage offer and remains subject to the lender’s checks, valuation and underwriting. Legal advice and property surveys should be obtained from appropriately qualified professionals.
Can I Get A Mortgage In Dorset If I Am Self-Employed, A Company Director Or A Contractor?
Potentially, yes. Lenders do not all assess self-employed, company-director and professional contract income in the same way. Depending on your circumstances, they may consider accounts, tax calculations, salary and dividends, retained profits or current contracts.
Conrad Financial Services can review how you earn and research suitable options. Mortgage availability remains subject to lender criteria, affordability checks and assessment.
Can Coastal, Rural Or Leasehold Properties In Dorset Affect A Mortgage Application?
They can. The lender will assess the individual property as well as the applicant. For example, construction, condition, lease terms, service charges, access, flood information or intended use may be relevant, depending on the home.
Your conveyancer and surveyor should provide the relevant legal and property advice. Conrad Financial Services can consider the information that affects the mortgage, but a Dorset postcode alone does not determine lender acceptance.
When Should I Review My Remortgage Options?
It can be useful to start before your current deal ends, allowing time to compare a new deal with your existing lender against remortgaging elsewhere. The right timing depends on your present mortgage, early repayment charges, circumstances and future plans.
A lower interest rate does not necessarily mean a lower overall cost after fees and charges. Any recommendation follows an individual assessment.
Can I Arrange Protection Alongside A Mortgage Or Separately?
Yes. Conrad Financial Services can discuss life insurance, critical illness cover and income protection alongside a mortgage or as a separate protection enquiry.
The appropriate type and amount of cover depends on your needs, existing arrangements, employer benefits, savings and budget. Cover is subject to the insurer’s terms, exclusions, underwriting and acceptance.
What Does Mortgage Advice From Conrad Financial Services Cost?
Your initial conversation is free. Conrad Financial Services charges a non-refundable mortgage advice fee of £500, payable on application.
The service and applicable fee will be explained before you decide whether to proceed. Other lender, valuation, legal or property-related costs may also apply depending on the transaction.
Ready to take the next step?
Let’s Talk About Your Mortgage And Protection Plans
If you live in England or Wales, start with a clear conversation about your circumstances and what you want to achieve.